Commodity
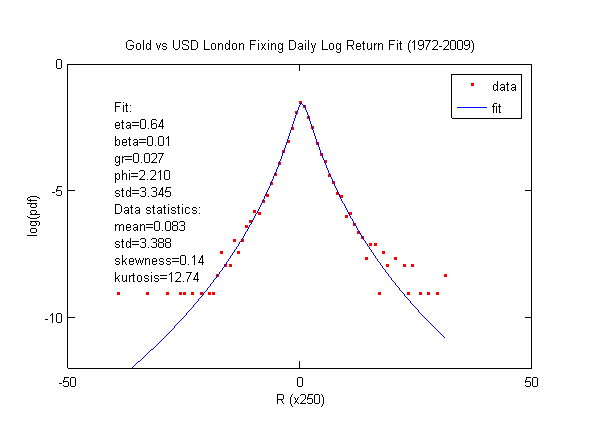
Gold against the US dollar
Positive skew when volatility rises. The fit keeps its high kurtosis without a large negative tail.
Quantitative finance
2008 to 2026
Tail risk is omnipresent
Our world is more volatile than we want to admit. This is a working archive of the distribution that puts fat tails, asymmetry and finite moments in one measurable frame.
Proposed by Stephen Lihn in 2008 and extended by the Poisson subordinated distribution in 2012.
The proposition
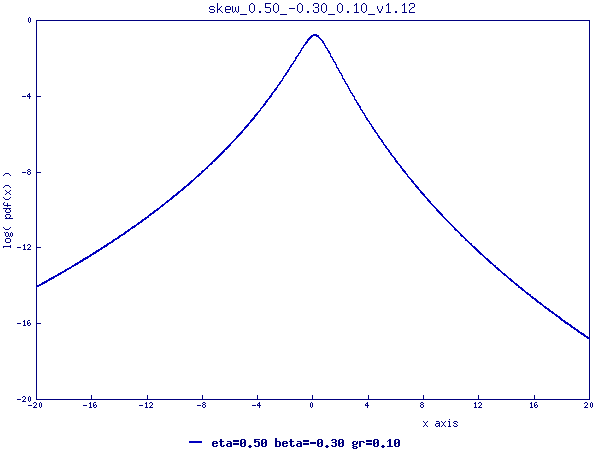
This website presents the skew lognormal cascade distribution and the Poisson subordinated distribution that followed. Evidence from currencies, commodities, Treasury yields, volatility and equity indices points to the same conclusion: tail risk is everywhere.
Extreme moves appear far more often than a normal model predicts.
A skew parameter controls the asymmetry of the distribution.
The distribution converges to the normal form and keeps its moments finite.
The evidence
With this distribution, a large portion of the tail risk in the financial market can be measured quantitatively. The archive treats the fit as evidence, not decoration.
A fat tail fit needs at least about 4,000 data points. That means roughly 15 years of daily data to begin. The studies here use longer records where they are available.
The mean is usually very small compared with the width of the daily return distribution. Long term growth is almost negligible next to the daily fluctuation. That is evidence that day traders live in a different world from long term investors.
The distribution exhibits fat tails, asymmetry tunable by a skew parameter, convergence to the normal distribution and finite moments.
These properties make it useful in financial applications. The work also points to a larger question: why should the volatility of volatility appear in so many unrelated markets?
Mathematical frame
The original equation plates are retained below. The analytic paper sets out the moments, cumulants, Taylor expansions and the numerical method.
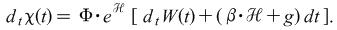
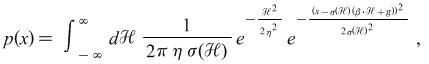
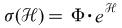
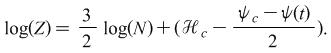
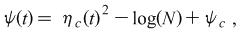
The model starts from a continuous time equation for log price. The higher order randomness hypothesis supplies the stochastic source of the cascade. A leakage term links large volatility with large negative returns.
The static distribution is the object used in the data atlas. Its parameters control tail fatness, skew and growth. The symmetric case is the cleanest entry point; the skew case adds the asymmetry seen in equity, oil and volatility indices.
The scaling argument extends the same logic to the whole market. If the capital distribution has a lognormal cascade structure, the market index inherits fat tails. The contraction and expansion of that distribution is the driving force behind bull and bear cycles.
Scaling and equilibrium
Total market value is proportional to the three halves power of the number of stocks. It is not Sarnoff's linear law, Metcalfe's n squared law or Reed's exponential law.
Data atlas
Each fit keeps its source note, chart and parameter reading. The series are ranked by kurtosis in the applications index.
Featured fit
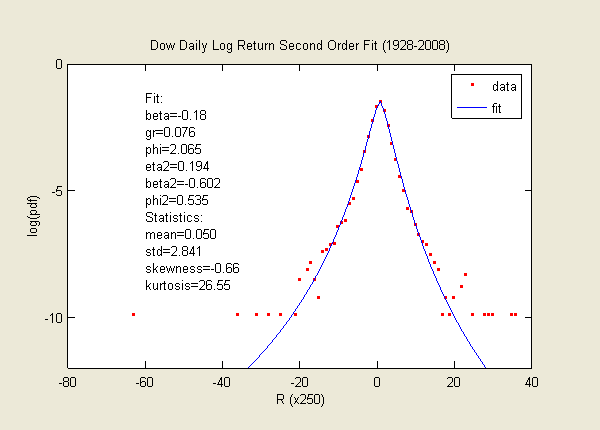
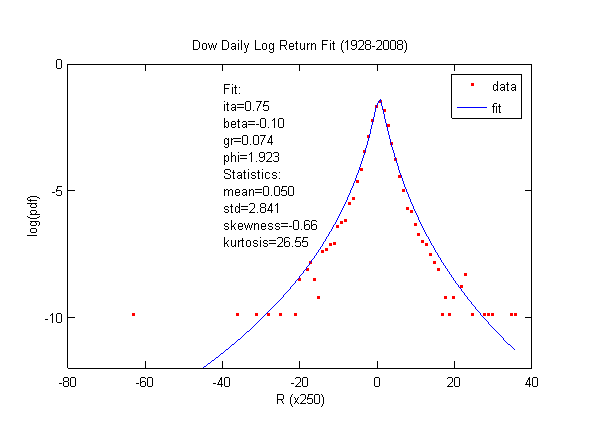
The longest equity record in the atlas. Daily Dow returns from 1928 to 2008 show the most prominent fat tails and require the higher order fit.
Commodity
Positive skew when volatility rises. The fit keeps its high kurtosis without a large negative tail.

Volatility
Volatility rises quickly and relaxes slowly. Mean reversion keeps the price spikes from sticking.
Working papers
Papers are hosted on SSRN and as PDFs in this archive. The sequence runs from the first skew lognormal cascade paper in 2008 to the Poisson subordinated distribution in 2012.
A new Poisson subordinated distribution is proposed to capture major leptokurtic features in log return time series of financial data. It is intuitive, easy to calculate and converges quickly. It fits historical daily log return distributions for currencies, commodities, Treasury yields, VIX and the DJIA, and serves as a viable alternative to the more sophisticated truncated stable distribution.
Subordination / Poisson / financial data / fat tail / leptokurtoticAbstract only on the current server
This working paper is an excerpt on the recent finding of the network effect in the stock market. I summarize the three halves power law: the total value of the stock market is proportional to the three halves power of the number of stocks. The law is based on several intuitive assumptions about a many body stochastic system. The hypothesis of an optimal volatility equilibrium is introduced as a pillar of the law. Such a system must adjust itself around a level of optimal volatility in order to survive as a viable market. The connections to Fernholz's diversity index and Clark's lognormal subordinated process are discussed. The hypothesis also indicates that investing in a large market does not guarantee the benefit of diversification as prescribed in modern portfolio theory.
Network effect / volatility / lognormal cascade / fat tails / stochastic portfolio theoryA short note on subordinated processes and the lognormal cascade distribution, placed beside Clark's 1973 paper in this archive.
Subordinated process / lognormal cascade distribution / P. K. ClarkThe paper presents the general theory of higher order skew lognormal cascade distributions as a mathematical extension of the earlier skew lognormal cascade distribution. The second order distribution incorporates fat tails into volatility, that is, the volatility of volatility. It handles very heavy tails and high kurtosis in high frequency financial time series. It accurately fits daily Dow log returns over 80 years, with kurtosis 26.
The framework offers a new way to study capital distribution, firm size distribution, the market index and market entropy. In the context of stochastic portfolio theory, it reveals that the origin of fat tails in market index fluctuations is the lognormal cascade structure of capital distribution. A simple stochastic model shows that contraction and expansion of the underlying capital distribution is the fundamental driving force of bull and bear market cycles and market volatility over the past 20 years.
A stochastic equation establishes the relation between the market index and the capital distribution, the lognormal cascade equation. This shows that market index fluctuations are a natural mathematical consequence of stochastic calculus on a market portfolio with exponentially distributed weights. The phenomena of fat tails should exist everywhere in the financial system.
Lognormal cascade / fat tails / capital distribution / stochastic portfolio theoryA continuous time scale invariant Brownian motion (SIBM) equation is developed to investigate the dynamics of the stock market. It solves the fat tail distribution of the stock universe and the DJIA time series, and it models volatility clustering in the DJIA. The equation is transformed from the Langevin equation into a fractal expression involving an infinite array of random walks. It predicts an elegant way of generating the skew form of the lognormal cascade distribution (Kolmogorov and Mandelbrot), which describes the static log return distribution in the financial market as well as the velocity distribution in Lagrangian turbulence.
The higher order randomness (HORN) hypothesis is introduced as the stochastic source of the cascade distribution. A leakage term from HORN models the covariance between large volatility and large negative return. A volatility model based on two SIBM processes models volatility autocorrelation. Volatility half times of 20 days and 300 days are extracted from DJIA data. The model generates static log return distributions from 10 days to 320 days that match DJIA data satisfactorily. It also suggests an alternative interpretation of the volatility smile and skew observed in the options market. The relation between the SIBM model and the multifractal random walk model is examined, yielding a simplified SIBM model that could be useful in finance.
Lognormal cascade / fat tail / volatility clustering / multifractalThe paper studies the skew lognormal cascade distribution, which is the static solution of the simplified SIBM model (Lihn 2008, SSRN: 1149142). Both the symmetric and the skew forms are studied. The analytic formula for the raw moments and cumulants is calculated. The implication for the multiscaling property is also studied for the symmetric distribution. Taylor expansions of the distributions and their logarithms are carried out.
An alternative Taylor expansion method improves the convergence of the power series for numerical computation of the probability density function. The method can be implemented via a computer algebra system and enables the numerical algorithm to produce high precision results.
Lognormal cascade distribution / Taylor expansion / fat tailWays in